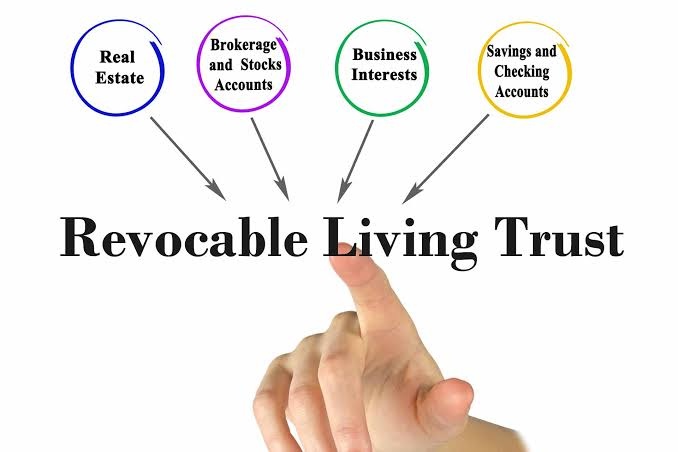
Revocable living trusts are often discussed as useful estate planning tools for managing assets during life and providing instructions for their distribution after death. They can offer flexibility and may help address certain planning objectives, but they are not automatically the right solution for every individual or family.
Before choosing any estate planning structure, it is important to understand both its potential benefits and limitations. The disadvantages of revocable living trusts can include higher upfront costs, ongoing administrative responsibilities, funding requirements, and limitations regarding asset protection and tax planning.
Understanding these considerations can help individuals make more informed decisions about whether a revocable living trust fits their personal, financial, and family circumstances.
One of the first factors people may notice is the cost of creating a revocable living trust.
A trust-based estate plan can require more detailed preparation than a simple will. The documents must clearly establish how the trust operates, identify trustees and beneficiaries, and provide instructions for managing and distributing assets.
The complexity of the individual's estate can also affect the amount of planning required. Families with multiple properties, business interests, blended family relationships, or significant investments may require more customized provisions.
Although upfront costs should not be the only factor when making an estate planning decision, individuals should understand the financial commitment involved.
Creating a trust document is only one part of the process. Assets generally need to be properly transferred or titled in a manner consistent with the trust plan.
This may involve changing ownership records for real estate, transferring certain financial accounts, or updating documentation related to other property.
If important assets are not properly coordinated with the trust, the intended planning benefits may be reduced. In some situations, assets left outside the trust could still require additional administration after death.
For this reason, proper funding and periodic reviews are important parts of maintaining a trust-based plan.
A revocable living trust may require continuing attention during the creator's lifetime.
When new assets are acquired, individuals may need to consider whether those assets should be incorporated into the trust plan. Changes in property ownership, financial accounts, or family circumstances can also require updates.
Recordkeeping may become more important when assets are managed through a trust structure.
While these responsibilities may be manageable, they can create additional administrative work compared with relying solely on simpler estate planning documents.
Individuals who prefer minimal ongoing management should consider whether they are willing to maintain the structure properly over time.
One of the most common misunderstandings is the belief that a revocable living trust automatically protects assets from creditors.
In many circumstances, because the person creating a revocable trust retains significant control over the assets, those assets may not receive the same type of creditor protection associated with certain other legal structures.
Asset protection depends on many factors, including the type of planning arrangement, ownership structure, applicable law, and the individual's circumstances.
People seeking creditor protection should avoid assuming that a revocable trust alone will accomplish that goal.
Another important consideration involves taxation.
A revocable living trust does not automatically eliminate estate, income, or other taxes simply because assets are placed into the trust.
The tax consequences of estate planning depend on numerous factors, including asset values, ownership arrangements, applicable exemptions, and current federal and state laws.
Tax planning may require additional strategies beyond a basic revocable trust.
Individuals should therefore evaluate tax objectives separately rather than assuming that creating a trust will automatically produce significant tax savings.
Trusts are sometimes associated with greater privacy than probate proceedings. However, privacy outcomes can depend on how assets are owned, how the estate is structured, and the applicable legal requirements.
Certain information may still become available through other legal or financial processes.
Individuals should therefore avoid assuming that a trust guarantees complete confidentiality under every circumstance.
Privacy can be an important planning objective, but it should be evaluated alongside other goals rather than treated as an automatic result.
Selecting a trustee is an important decision.
The trustee may eventually be responsible for managing property, maintaining records, communicating with beneficiaries, and following the instructions contained in the trust.
A family member may understand the creator's wishes and family relationships, but serving as trustee can also create significant responsibilities.
In some situations, disagreements between beneficiaries and trustees may arise. Choosing the wrong person could create administrative difficulties or family conflict.
Individuals should carefully consider whether a proposed trustee has the time, financial judgment, organizational ability, and willingness to serve.
The disadvantages of revocable living trusts may become more noticeable when an estate includes complicated assets.
Real estate in multiple locations, closely held businesses, valuable collections, and digital assets can require additional planning and administration.
For example, business interests may involve operating agreements and management concerns, while digital assets may require secure access information and specialized documentation.
These issues do not necessarily mean a trust is inappropriate. However, they demonstrate why a trust should be designed around the individual's specific circumstances rather than using a one-size-fits-all approach.
A revocable living trust generally does not eliminate the need for all other estate planning documents.
Individuals may still need documents addressing assets that are not held by the trust, personal decision-making during incapacity, healthcare preferences, and other legal matters.
A comprehensive plan often involves coordinating multiple documents and ownership arrangements.
This means that creating a trust should not be viewed as completing every aspect of estate planning. Regular reviews and coordination remain important.
Estate plans should evolve as life changes.
Marriage, divorce, the birth of children, changes in financial circumstances, new business ventures, and significant asset acquisitions can all affect an existing trust plan.
Failing to update documents or review asset ownership can result in a plan that no longer reflects current intentions.
Individuals should establish a habit of reviewing their estate plan periodically and after major life events.
The answer depends on the individual's circumstances.
For some people, the flexibility and asset-management features of a revocable living trust may support important planning objectives. For others, the costs and administrative requirements may outweigh the potential benefits.
The key is understanding how the structure works and what responsibilities come with it.
One of the most important disadvantages of revocable living trusts is that they are sometimes presented as a universal solution when estate planning should always be based on individual needs.
A revocable living trust can be a valuable estate planning tool, but it is not automatically the best choice for every family. Upfront costs, ongoing administration, proper funding requirements, limited asset protection, and the need for additional planning documents should all be considered.
Before creating any trust, individuals should evaluate their assets, family circumstances, long-term goals, and willingness to manage the structure over time.
With careful planning and qualified professional guidance, families can better understand their available options and create an estate plan that reflects their specific needs rather than relying on a one-size-fits-all solution.
This post has been authored and published by one of our premium contributors, who are experts in their fields. They bring high-quality, well-researched content that adds significant value to our platform.




Trending Buzz is your trusted source for trending news, viral stories, entertainment, technology, lifestyle, and informative content. Discover what's buzzing around the world every day.
